Age Pension payments increase from 20 September 2026, with higher maximum fortnightly payments for both singles and couples.

The Age Pension is an important source of retirement income for many Australians. Even for retirees with substantial superannuation and other investments, a part Age Pension can contribute to the overall financial strategy.
From 20 September 2026, several important changes will come into effect. The maximum Age Pension increases, the upper income and assets test thresholds rise, and deeming rates increase.
While the higher pension rates are welcome, the changes demonstrate why Age Pension planning is rarely as simple as looking at one number.
"Your entitlement depends on how your income, investments and assets interact with Centrelink rules."
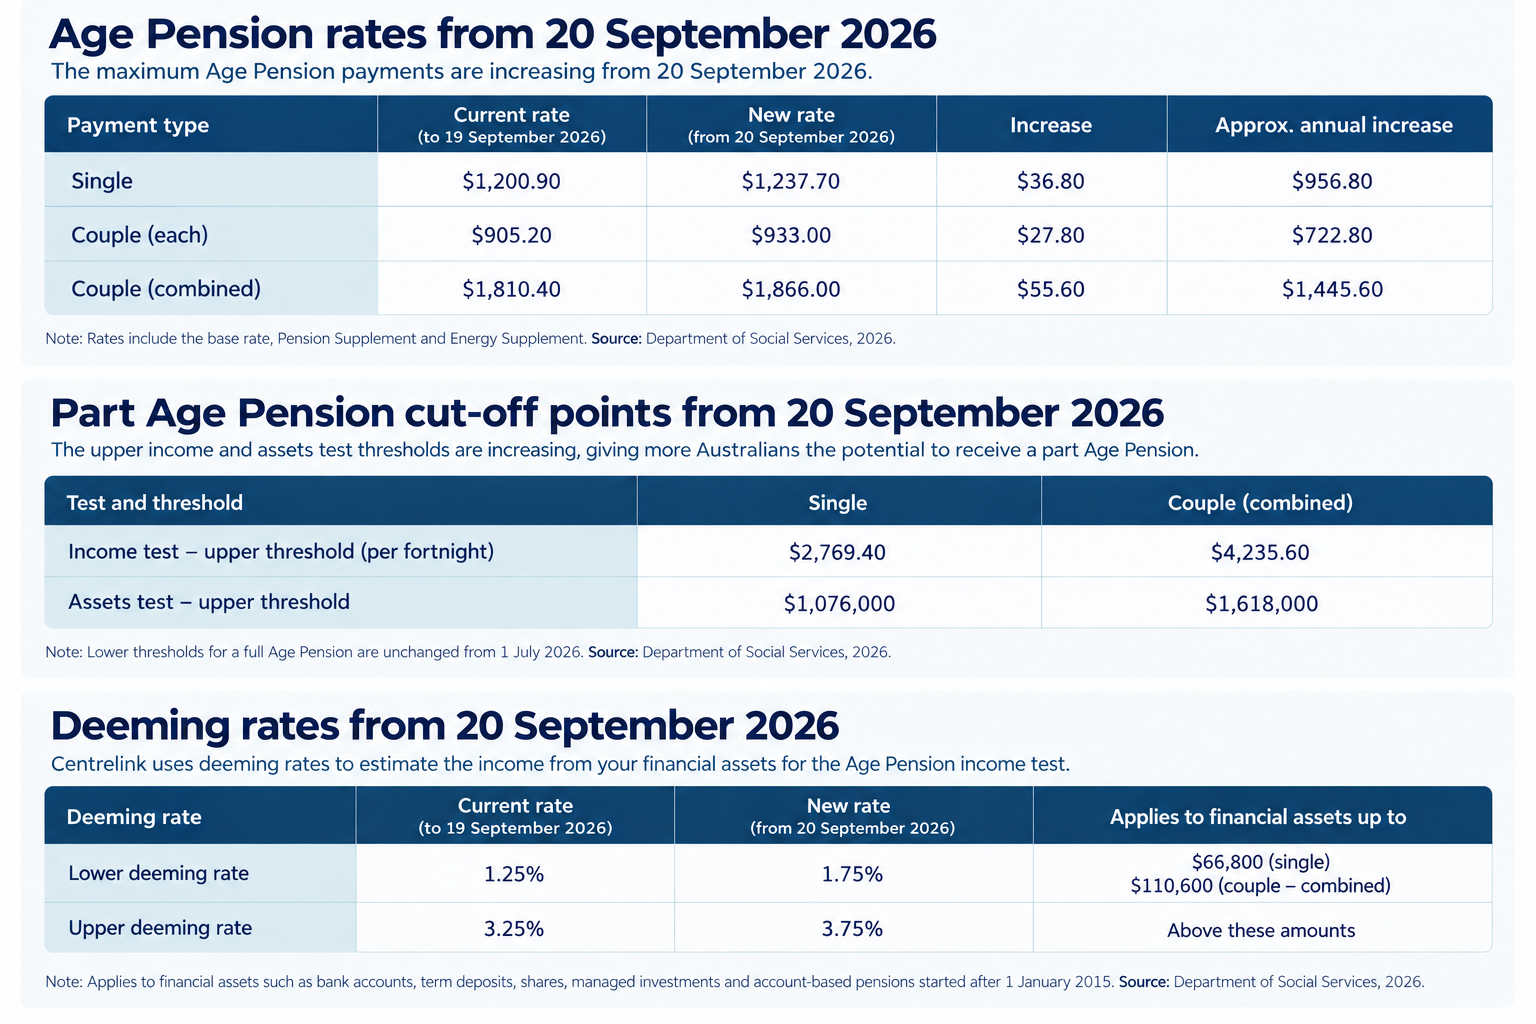
From 20 September, the maximum Age Pension for a single person increases by $36.80 per fortnight to $1,237.70. For couples living together, the maximum rate increases by $27.80 each to $933.00 per fortnight. That provides a combined maximum payment of $1,866.00 per fortnight.
For a couple receiving the maximum pension, that represents an increase of approximately $1,445.60 over a full year. For a single pensioner, the annual increase is approximately $956.80.
However, not every pensioner will receive the maximum increase.
The Age Pension is means-tested. Centrelink applies both an income test and an assets test, with the test producing the lower pension entitlement determining how much you receive.
From 20 September, the upper thresholds determining when a part Age Pension reduces to zero are increasing. The lower thresholds applying to the full Age Pension are not changing in September. They were adjusted on 1 July 2026.
The movement in the upper thresholds may be significant for retirees sitting around the boundary for part-pension eligibility. Someone who previously had slightly too many assessable assets or too much assessable income may find their position changes. This is one reason we believe Age Pension eligibility should be reviewed regularly.
There is another change retirees need to consider. Centrelink does not use the actual income earned from financial investments when applying the Age Pension income test. Instead, it uses prescribed deeming rates to estimate the income generated by those financial assets.
From 20 September, the lower deeming rate increases from 1.25% to 1.75%, while the upper rate increases from 3.25% to 3.75%.
So, what does this mean for singles and couples?
For singles, the lower rate applies to the first $66,800 of financial assets, and the higher rate applies to amounts above that threshold. For couples, the lower rate applies to the first $110,600 of combined financial assets, with the higher rate applying to the balance. Financial assets that may be subject to deeming include bank accounts, term deposits, shares and managed investments.
For some pensioners, a higher deemed income could offset part of the benefit provided by the September pension increase.
With the changes, the important question isn’t simply, “How much Age Pension can I get?” The more appropriate question is: “How do all my financial resources work together”
The Age Pension may be one component. Superannuation pensions, investment income, cash reserves and other assets also contribute. How those resources are structured influences your income, tax position, flexibility and potentially your Centrelink entitlement.
The objective should never be to make financial decisions only to maximise the Age Pension. Instead, your Age Pension position should be considered as part of your complete retirement strategy.
These changes create an opportunity. As we know, rules change, markets shift, spending habits fluctuate, and investment balances rise and fall. On top of that, priorities can pivot throughout retirement.
At First Financial, we model these different components together. We can help you understand how your superannuation, investments, retirement income and potential Centrelink entitlements interact and what they mean for your longer-term financial position.
If the September Age Pension changes affect you, or you’re approaching retirement and want to better understand your potential entitlement, now may be a good time to review the numbers.
“If these changes affect you, now is a good time to review the numbers.”
The team at First Financial comprises financial experts who help hundreds of Australians retire well and make informed, intelligent financial decisions. We cover everything from retirement and financial advice, investment and wealth management, superannuation and SMSF, insurance, tax, aged care, legal and lending services.
Contact us for holistic, well-rounded financial management strategies.

Age Pension payments increase from 20 September 2026, with higher maximum fortnightly payments for both singles and couples.
Higher upper-income and assets test thresholds may expand eligibility, particularly for retirees who are currently close to the cut-off for a partial Age Pension.
Higher deeming rates could affect your entitlement, as Centrelink will assess more deemed income from financial assets such as bank accounts, term deposits, shares and managed investments.
Review the Age Pension as part of your complete retirement strategy. Changes to Centrelink rules can affect how your superannuation, investments, cash reserves and pension entitlements work together.
Every client journey begins with a conversation. We look closely at where you are now, what matters to you, and what’s possible. Then we structure our advice to match.

A clear, personalised path to your financial goals.

Proactive strategies to maximise your tax savings.

Tailored plans aligned with your goals and risk profile.

Regular guidance to keep your plan on track.
Retired business owner
After decades of running a successful pharmacy, John sought financial guidance to simplify decision-making and support long-term planning.
“I feel genuinely supported by First Financial. I can ask anything, and there’s no pressure, just clear advice and real care. The money’s growing, I’m not stressed about it, and I feel completely at ease for the first time. I don’t miss work, but I’d miss the support I get from First Financial.”
Newly retired
As retirement neared, Larry and Virginia were ready to enjoy travel, family, and freedom, without uncertainty. A friend recommended First Financial, and from the first meeting, they had a clear plan, a safety net, and people they trusted.
“We’ve travelled the world, Europe, Sri Lanka, Vietnam, without once stressing about the money. They made everything feel simple and gave us the confidence to live well. We feel secure because we know exactly where we stand, and that peace of mind means everything.”
Retired widow
Lyn stepped into financial management for the first time after her husband's passing. With patience and care, First Financial supported her through grief, learning, and empowerment.
“After my husband passed, I was completely unsure where to start. First Financial gave me the space to learn, to ask questions, to grow confident. They drew a diagram that I still have. And now, I sleep well at night knowing I’ve got someone in my corner.”
Retired
Jan's husband managed the finances until entering aged care. Jan gradually stepped into the financial picture with First Financial’s support.
“The money just comes in. I don’t have to think about it. And I know they’re always there. They’ve always been there in the background, just quietly making things work.”
Retired and semi-retired
Referred by friends who were helped through aged care, Craig sought secure financial guidance after inheriting funds.
“We feel very secure with First Financial, the income just comes in, and we know everything is being looked after. It’s not just safe, it’s smart. We’ve recommended them to others because we genuinely believe in the team.”
Early retirement and working professional
When Tim received an overseas medical settlement, he and Adam had just 14 days left in a 90-day window. They needed clear guidance, fast. A referral led them to First Financial.
“We’re in totally different life stages, but First Financial built a strategy that supports us both. From urgent legal steps to ethical investing, they handled every detail with calm, care, and real expertise. It’s financial freedom without compromise, and we couldn’t have done it without them.”
Not necessarily. The amount you receive depends on your individual circumstances and how Centrelink’s income and assets tests apply to you.
Potentially. If you were previously just above the upper income or assets test threshold, the increases from 20 September may bring you within the eligibility limits.
Yes. Changes to the pension rate and upper means-test thresholds could increase your entitlement, while higher deeming rates could increase the income Centrelink assesses from your financial investments.
From 20 September, the lower deeming rate rises from 1.25% to 1.75% and the upper rate from 3.25% to 3.75%. If you hold financial assets such as bank deposits, term deposits, shares or managed investments, this could increase your assessed income and potentially affect your pension entitlement.
They can. Centrelink generally applies the prescribed deeming rates to relevant financial assets rather than using the actual income those investments earn when assessing your Age Pension under the income test.
Your investment and retirement decisions should consider your overall financial position rather than focusing solely on maximising the Age Pension. Superannuation, investments, cash flow, tax, risk and your longer-term retirement objectives should all form part of the decision.
Yes. First Financial can review how your superannuation, investments, other financial resources and potential Centrelink entitlements work together and help you understand what the changes could mean for your retirement strategy.
Yes, understanding your potential Age Pension position before retirement can help you make more informed decisions about superannuation, investments and retirement income. Contact First Financial to discuss how Centrelink entitlements can be considered as part of your broader retirement plan.